Ongoing shifts in trade routes and raw material shortages among traditional processing leaders are creating a unique foothold for the large-scale expansion of the processing sector.
The Black Sea Hub and the Reshaping of the Global Market
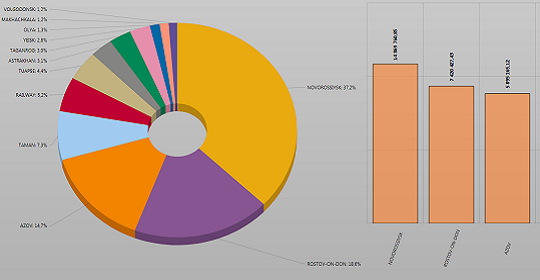
Restrictions on grain exports through traditional port terminals in the Sea of Azov and the Black Sea have unexpectedly served as a catalyst for the development of domestic processing.
The infrastructure crisis in the Black Sea region has sent a shockwave through global trade, triggering a major realignment of commodity flows. A defining feature of the current situation is that key global exporters of finished flour are rapidly losing their standing.
Global market leaders—who spent years building their businesses on the procurement of affordable raw materials—are now facing a severe shortage of supply. Without stable access to raw materials, processors in these countries can no longer maintain their former price competitiveness.
Compounded by domestic currency fluctuations in some regions and poor grain harvests in neighboring states, the positions of the industry’s long-standing leaders have been significantly shaken.
A Historic Opportunity for Domestic Processing
For the domestic flour-milling industry, the current situation presents a rare window of opportunity—a chance to transition from a niche supplier to a global leader.
Analysts forecast that by the end of the current agricultural season, flour export volumes could reach an all-time high, hitting a record 1.5 million tonnes.
Current disruptions in southern logistics are compelling businesses to act with agility and explore alternative transport corridors. Companies that possess their own terminal infrastructure in other regions—for instance, on the Baltic Sea—are successfully repurposing their capacity from shipping raw grain to transporting finished flour products.
This approach makes it possible to effectively bypass logistical bottlenecks in the south and steadily increase shipments to foreign markets, thereby cementing the companies’ reputations as reliable and stable partners.
Geographic Expansion and New Strategic Targets
Central Asia, Africa, and the Middle East have emerged as the primary focal points for sales expansion. Relevant government agencies are highly optimistic about the sector’s export potential and have set a new strategic development target: two million tonnes of finished products per year.
The eastward direction is a key driver of this growth. Asian trading partners are showing a manifold increase in their procurement, making this region the leading destination for Russian flour exports.
Central Asian and Middle Eastern nations have also firmly established themselves as major strategic buyers, actively replacing products from traditional suppliers with alternatives that offer better value and higher quality.
Historical Perspective and the Path to Volume Recovery
Looking back, the domestic flour-milling industry once reached record export levels of 1.25 million tonnes.
In subsequent periods, however, export volumes saw a significant correction—dropping by nearly half—largely due to the strengthening of the national currency and shifts in macroeconomic conditions.
In recent seasons, annual exports have stabilized at around half a million tonnes. The current calendar year, however, promises to be a turning point. Businesses are not only returning to long-term average performance levels but are also confidently announcing plans to surpass pre-crisis highs by diversifying their logistics and capturing global market niches that have opened up.