The scale of disruptions to Black Sea wheat supplies is comparable to the energy crisis in the Strait of Hormuz.
The crisis in the Black Sea region is driving a global restructuring of the grain market and threatening food security.
Black Sea Deadlock: Export Volumes Dwindle
Russia and Ukraine together control over 25% of the global wheat market. However, prolonged escalation and mutual strikes on port and logistics infrastructure have led to a critical drop in shipments.
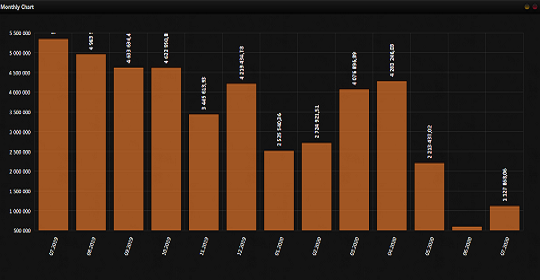
According to expert estimates, combined grain exports from the two countries fell by nearly half between July and September 2026 compared to the previous year.
The situation is exacerbated by rising diesel prices and a shortage of available grain elevator capacity; facilities are filled almost to the limit ahead of winter.
Logistical Shift and a Lack of Alternatives
Traditional maritime routes via the deep-water ports of Odesa and Novorossiysk are blocked or under constant threat.
Attempts to reroute commodity flows have proven largely ineffective:
Russian exports are partially shifting to overland transit via Kazakhstan, as well as to ports in the Baltic and Far East regions.
This extends delivery distances by thousands of kilometers and reduces profit margins for traders.
Ukrainian transit faces infrastructure constraints within the EU and stiff opposition from European farmers.
A shortage of personnel in the trucking sector—driven by mobilization-related restrictions—has created an additional hurdle.
Alternative logistics hubs, including Romania’s Constanța and Danube river ports, are overwhelmed and vulnerable to weather conditions.
Global Expansion in Search of New Grain Supplies
Supply disruptions are forcing major importers—such as Egypt and Southeast Asian nations—to urgently seek alternatives to Black Sea grain.
Sourcing patterns are shifting rapidly: Libya and Sudan are purchasing French wheat for the first time in years, while Turkey and the UAE have turned to suppliers in the Baltic states.
Increased demand is being observed in markets across Argentina, India, and Australia.
However, fully replacing the lost volumes is impossible. Summer heat in Europe and drought in the US have already reduced yields for the current season, and global reserves continue to dwindle.
Forecasts and Risks for the 2027 Harvest
Amidst the panic, wheat prices have hit a three-year high.
The market faces additional pressure from macroeconomic factors: the conflict between the US and Iran, rising fertilizer costs, and El Niño climate anomalies.
There are currently no comprehensive agreements in place regarding safe corridors.
The primary long-term threat to the agricultural sector is that the ongoing crisis will force farmers to reduce the acreage planted for next year’s harvest.
This creates a time bomb for the supply-demand balance throughout 2027.